

The property comprises a detached industrial warehouse located in Hayes, west London. The property is only five miles to the north of Heathrow and is in very close proximity to the M4 and M25. The Elizabeth Line station at Hayes is walking distance from the warehouse.
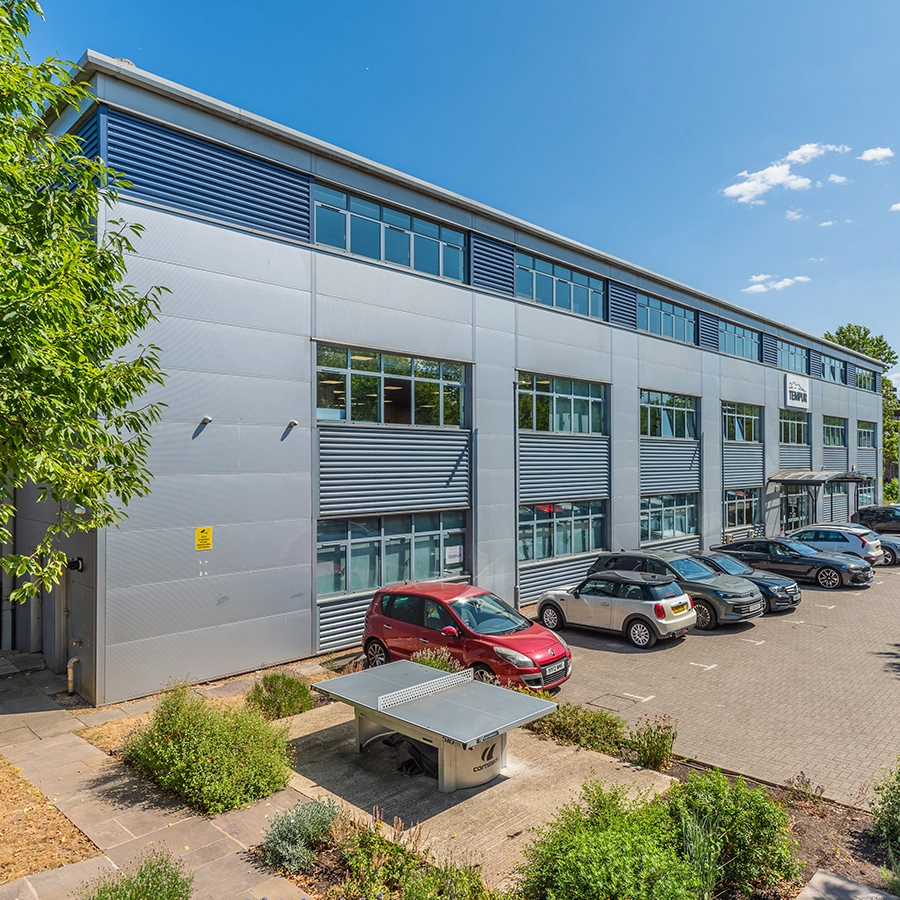
CPF acquired the freehold interest in June 2011. The purchase price was £5.7 million which reflected a yield to CPF of 8.6%. At purchase, the property was let to Tempur at a rent of £497,097 per annum on a lease that expired in October 2016. We extended the lease by five years in 2016 maintaining the rent at the same level. At the end of 2020 with less than a year until the lease was due to expire in October 2021 we again extended the lease by five years taking the expiry to October 2026, but this time increasing the rent to £674,638 per annum (+36%). In early 2026 with the upcoming lease expiry approaching in October, we agreed terms for a 10 year lease renewal (tenant break at year five) at a revised rent of £1,214,317 per annum which showed an 80% increase compared to the previous rent.
The asset has witnessed busy asset management over the years involving three separate lease renewals which have delivered an aggregate increase in rent of 144% since purchase. We have experienced no void, incurred no capex, given away no rent free and have the same tenant today as we did at purchase in 2011. The strength of the income growth over recent years has translated to significant capital growth of the asset and this property now sits within our top 15 holdings by value.
The property is a manufacturing warehouse located close to Nottingham with easy access to the M1 and is occupied by Turbine Surface Technologies Limited.
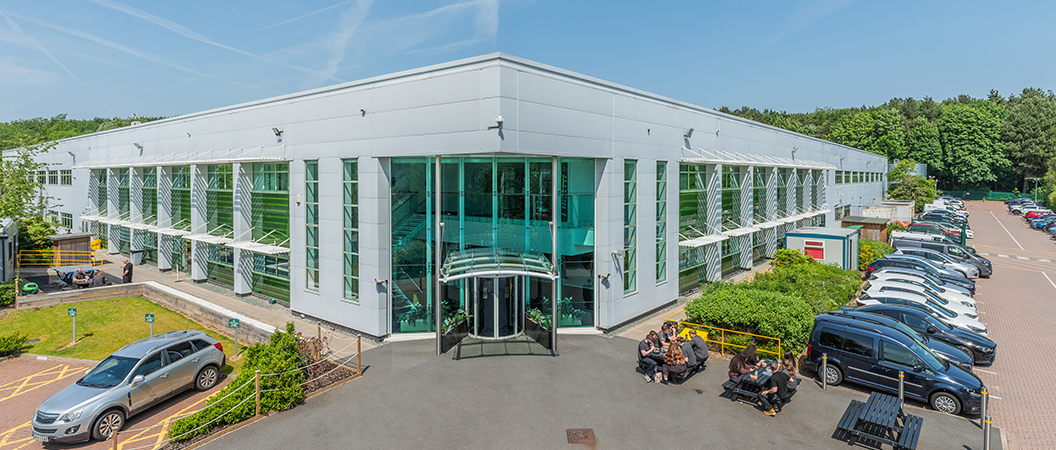
CPF acquired the virtual freehold interest (999 years) in September 2010, subject to a lease to Turbine Surface Technologies until December 2026 at passing rent of £433,843 per annum. The tenant’s business is 50% owned by Rolls Royce and they use the property for high-precision advanced manufacturing. The tenant has invested significant capex over the years into the property as part of their manufacturing activities.
Anticipating the lease expiry event in December 2026, we started negotiations with the tenant in 2025 to extend the lease. In early 2026 we completed a 25 year lease renewal commencing in December 2026 at a starting rent of £600,000 per annum (+38%), which extended the lease expiry to December 2051. The rent will be reviewed in 2031 and every fifth year thereafter in 2036, 2041 and 2046 on an upward only CPI-linked basis, collared at 2% per annum compound and capped at 4% per annum compound. There are no tenant breaks in the lease.
Our active management of the asset has converted the uncertainty around an imminent lease expiry event into a valuable 25 year index-linked income stream secured to a good quality tenant who has invested significant capital into the building whilst also securing a material increase in the rent. Since purchase up to the date we completed the lease extension, the asset had provided uninterrupted income to our investors for over 15 years providing almost £7 million of distributable income with a further 25 years of inflation-linked cashflow to come.
This property comprises a 48,000 sq ft office building located close to Farringdon Station in Central London. It was acquired in March 2011 for £23 million, reflecting a yield to the Fund of 7.06% and a capital value of £480 per sq ft. At the time, it was let to EHS Brann, a Franco-Spanish advertising company, for a further five years at a rent of £34 per sq ft. One of the main reasons for acquiring the building was the expected benefit of Crossrail delivery’s delivery in 2018.
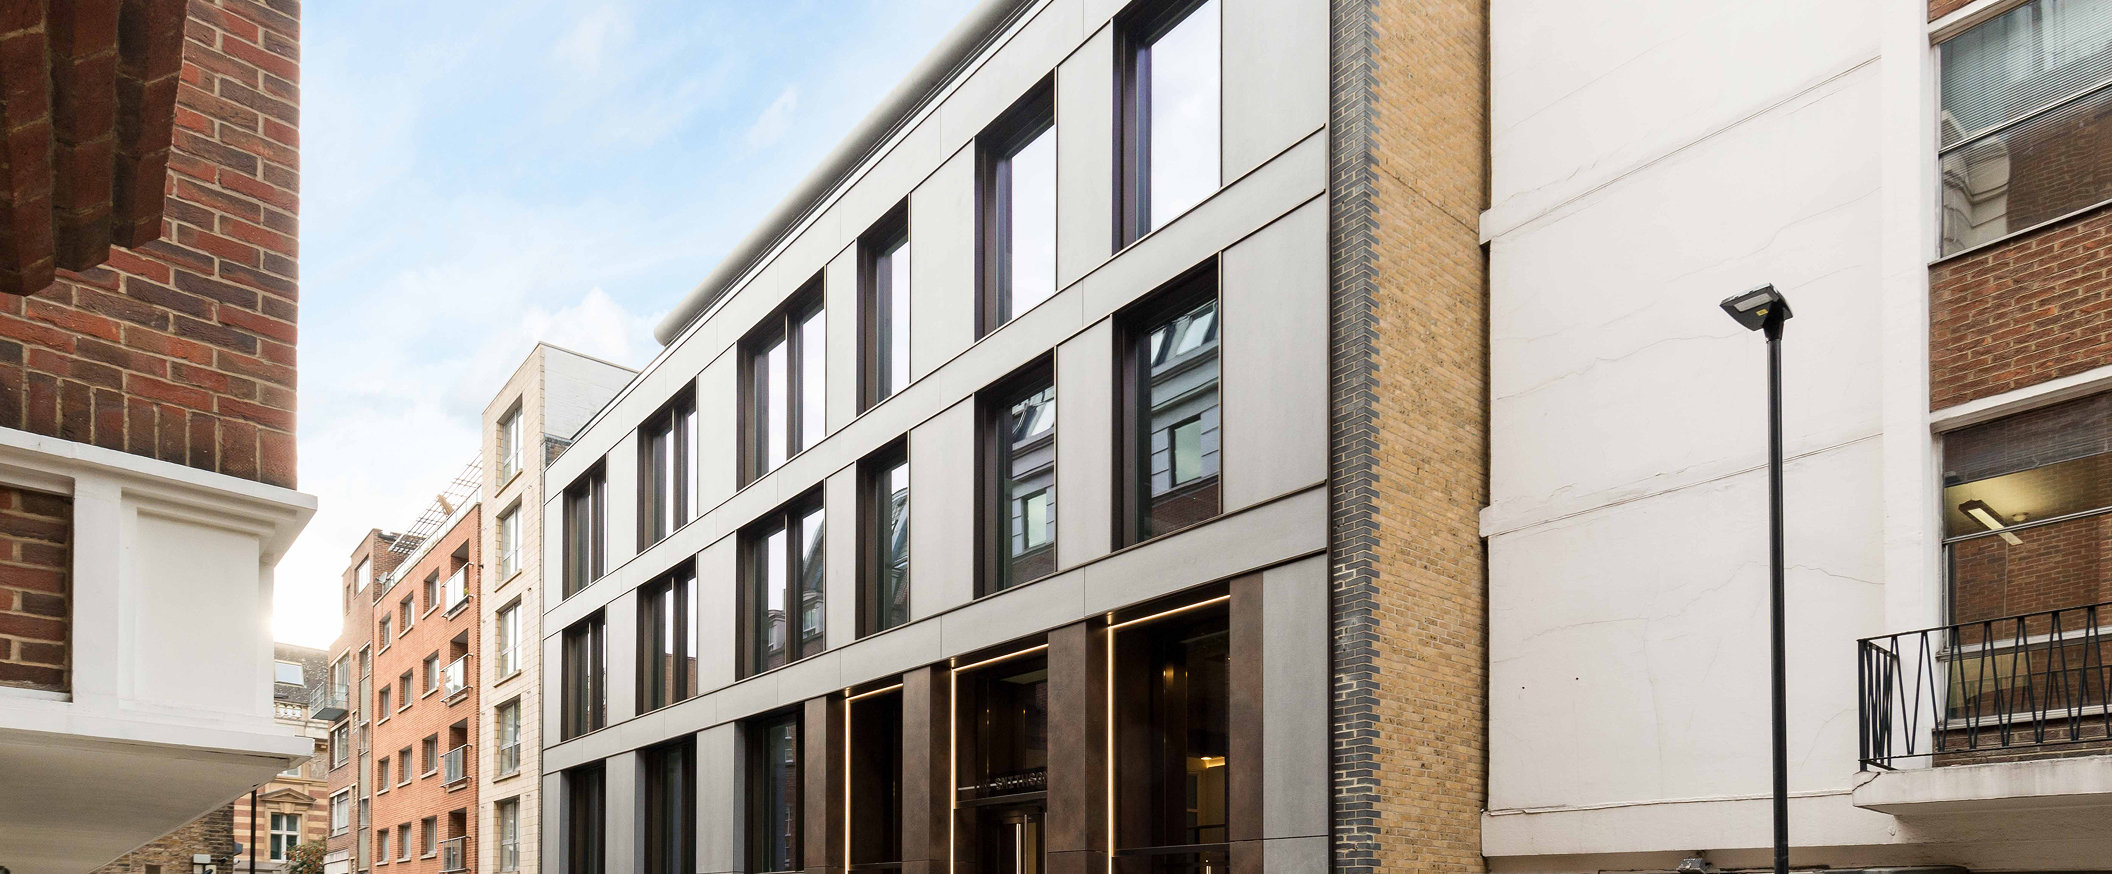
Shortly before the lease expiry in 2016, we agreed a short extension with the existing tenant and a dilapidations payment, enabling us to refurbish the building in spring 2017.
Before completion we signed an agreement for lease to pre-let 80% of the building to Macmillan Publishers Ltd, a major international publishing house founded in 1843. Now wholly owned by German media giant Holtzbrinck Publishing Group, Macmillan signed a new 15-year lease (with a break at year 10 on payment of a penalty) at £2.36 million per annum – an average of £65 per sq ft.
Planning permission was granted for a full-height reception area, a new facade and new windows, new mechanical and electrical services, some added floorspace and maximised natural light. The project also focused strongly on sustainability, providing 70 bike racks and seven showers, and aiming to improve the EPC rating from D (95) to B. The existing structure was retained to reduce waste and unnecessary use of resources.
The remainder of the building has been let to a technology company, Airsorted, which occupies the ground and lower-ground floors as their head office. We secured a premium rent above target, marking the end of a comprehensive refurbishment and repositioning.
The project was tendered at £175 per sq ft, with works beginning in Autumn 2017. Completion took place on 8 August 2018 – on schedule and under budget. The EPC score has increased to B (36) , compared with 35 for new builds.
The building now produces a rent of in excess of £3 million per annum – 83% higher than the rent before refurbishment – and has delivered income of over £11 million and capital growth of nearly £25 million (after deducting refurbishment costs). The over the seven-year ownership period exceeds 20% per annum.
This property comprises a motorway service area located at Junction 4 of the M54. We acquired the freehold interest in 2013 subject to a lease to Welcome Break expiring in November 2027.
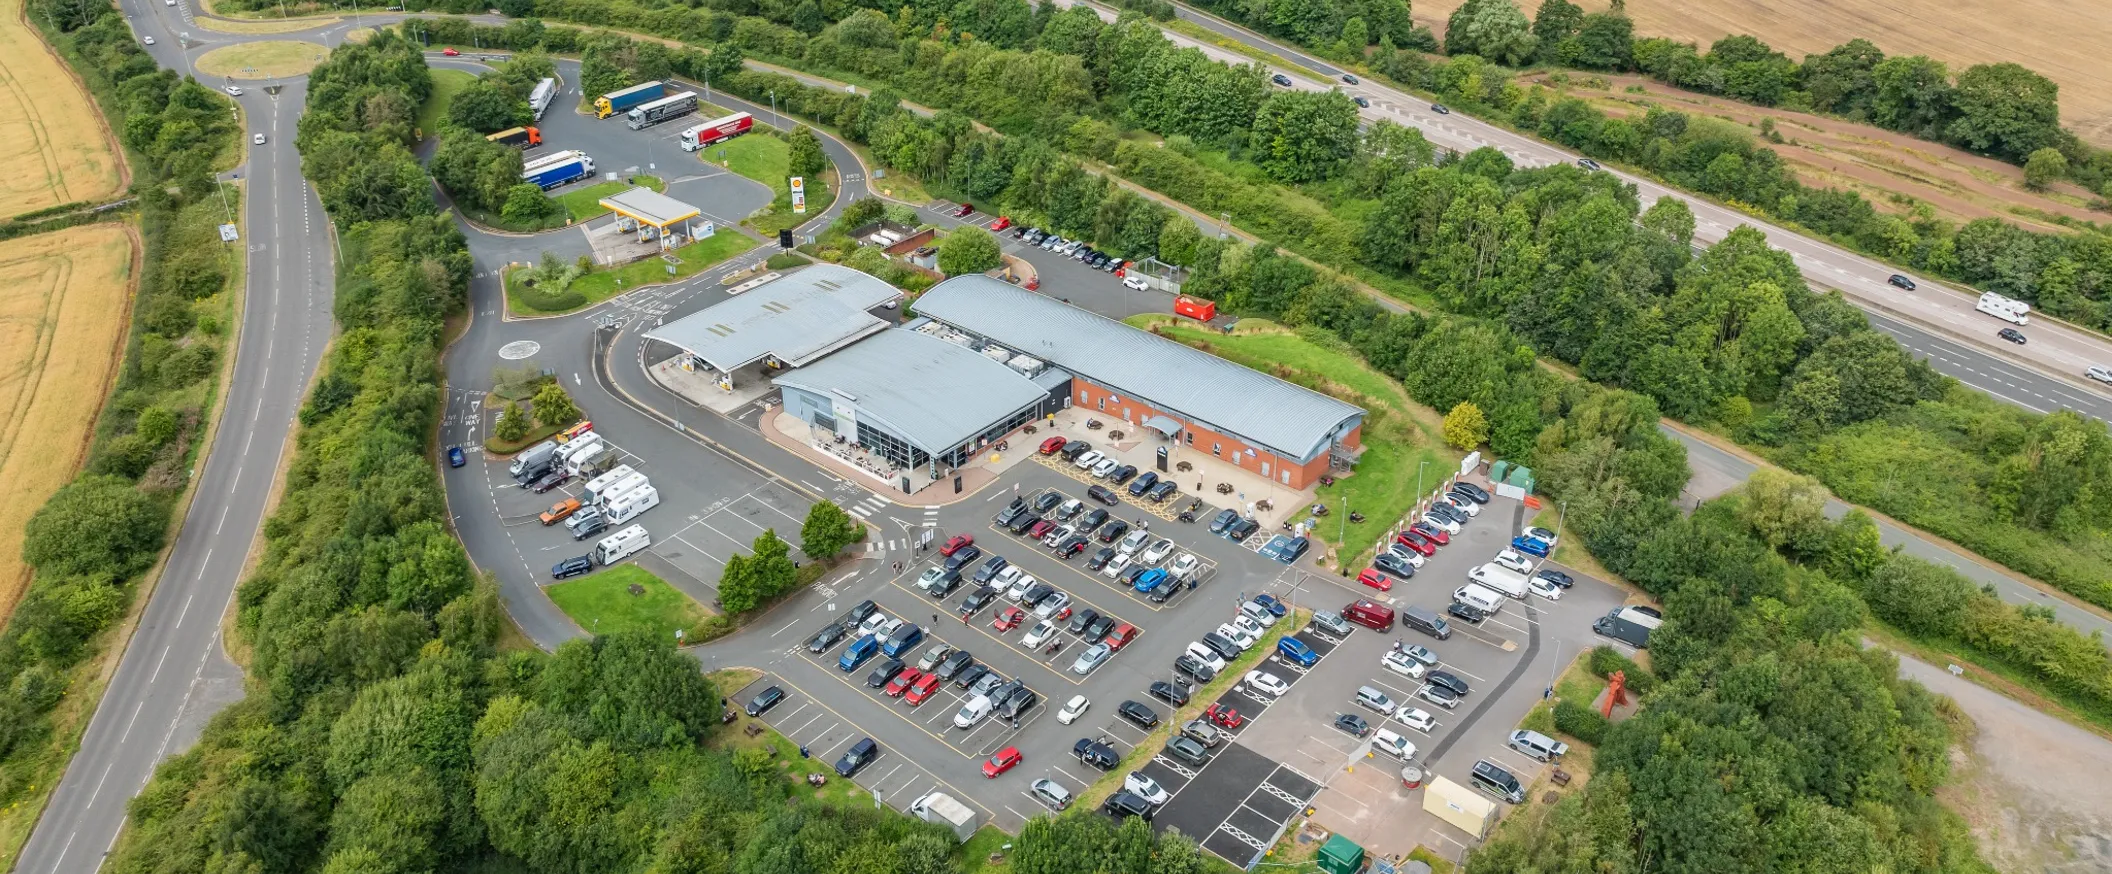
The rationale for acquiring the property was to secure a rare infrastructure holding to add to the Fund’s growing allocation to the Alternatives sector. The asset is operationally resilient to cyclical market conditions due to the captive audience and defensive nature of the sector so there is strong demand from occupiers to trade from these sites. Securing planning permission for motorway service areas is fraught with difficulties and high costs so existing assets benefit from an inherent lack of competition which is further underpinned by highways regulation restricting the development of future competition. This type of operational real estate – where the physical real estate is essential to the tenant’s business – also has high vacant possession values due to the scarcity of sites, high construction costs and deep demand from occupiers wanting to trade from these properties.
Motorway service area sites are often owned by the operators who are attracted to the combination of necessity fuel and EV charging revenue, blended with high margin retail sales and increasing dwell times from consumers. As the market evolves to more EV charging the high margin retail spend from consumers is only likely to increase further. Telford benefits from a Waitrose within the retail offer so the property is well placed to capitalise on this.
All of these factors have been tailwinds to the asset which has recently undergone a long term lease extension. The lease was due to expire in November 2027 and following negotiations with the tenant we have secured a 35 year lease extension taking the lease expiry date to November 2062 with no tenant breaks. The rent, which was £896,060 per annum when we purchased the asset in 2013 has risen to £1,147,033 per annum and we have agreed that this will further increase to £1,297,762 per annum from November 2027. The rent will benefit from 2.5% pa compound increases for the first 15 years of the extended lease and CPI linked rental increases for the following 20 years. The tenant did not receive any rent free or financial incentive to enter into the new lease which highlights the strategic and operational importance of the site to the tenant’s business. As part of the lease negotiation with the tenant we have agreed to the installation of a further 8 EV charging stations, paid for by the tenant, to add to the existing 19 charging stations on site.
Having benefited from uninterrupted and growing rent since purchase, this asset now has a very long term income stream secured to a good quality tenant which will continue to deliver compounding income returns to our investors. We are optimistic about the future prospects for this asset and will continue to work with the tenant to enhance the sustainability credentials as the market evolves towards electric vehicles.
This industrial property holding comprises two detached warehouses. Unit 1 is a temperature controlled warehouse let to BB&R and Unit 2 is a data centre let to Vodafone. The asset was acquired in 2018.
In early 2026 we completed a 15 year lease renewal with the existing tenant, Vodafone, at Unit 2. Following their lease expiry in April 2025, Vodafone was holding over at a rent of £263,445 per annum equating to £9.50 per sq ft. In 2025 we agreed terms for a new 15 year lease with no tenant breaks at an increased rent of £360,000 per annum, reflecting £12.98 per sq ft and an increase of 37%. No rent free of other incentive was given to the tenant.
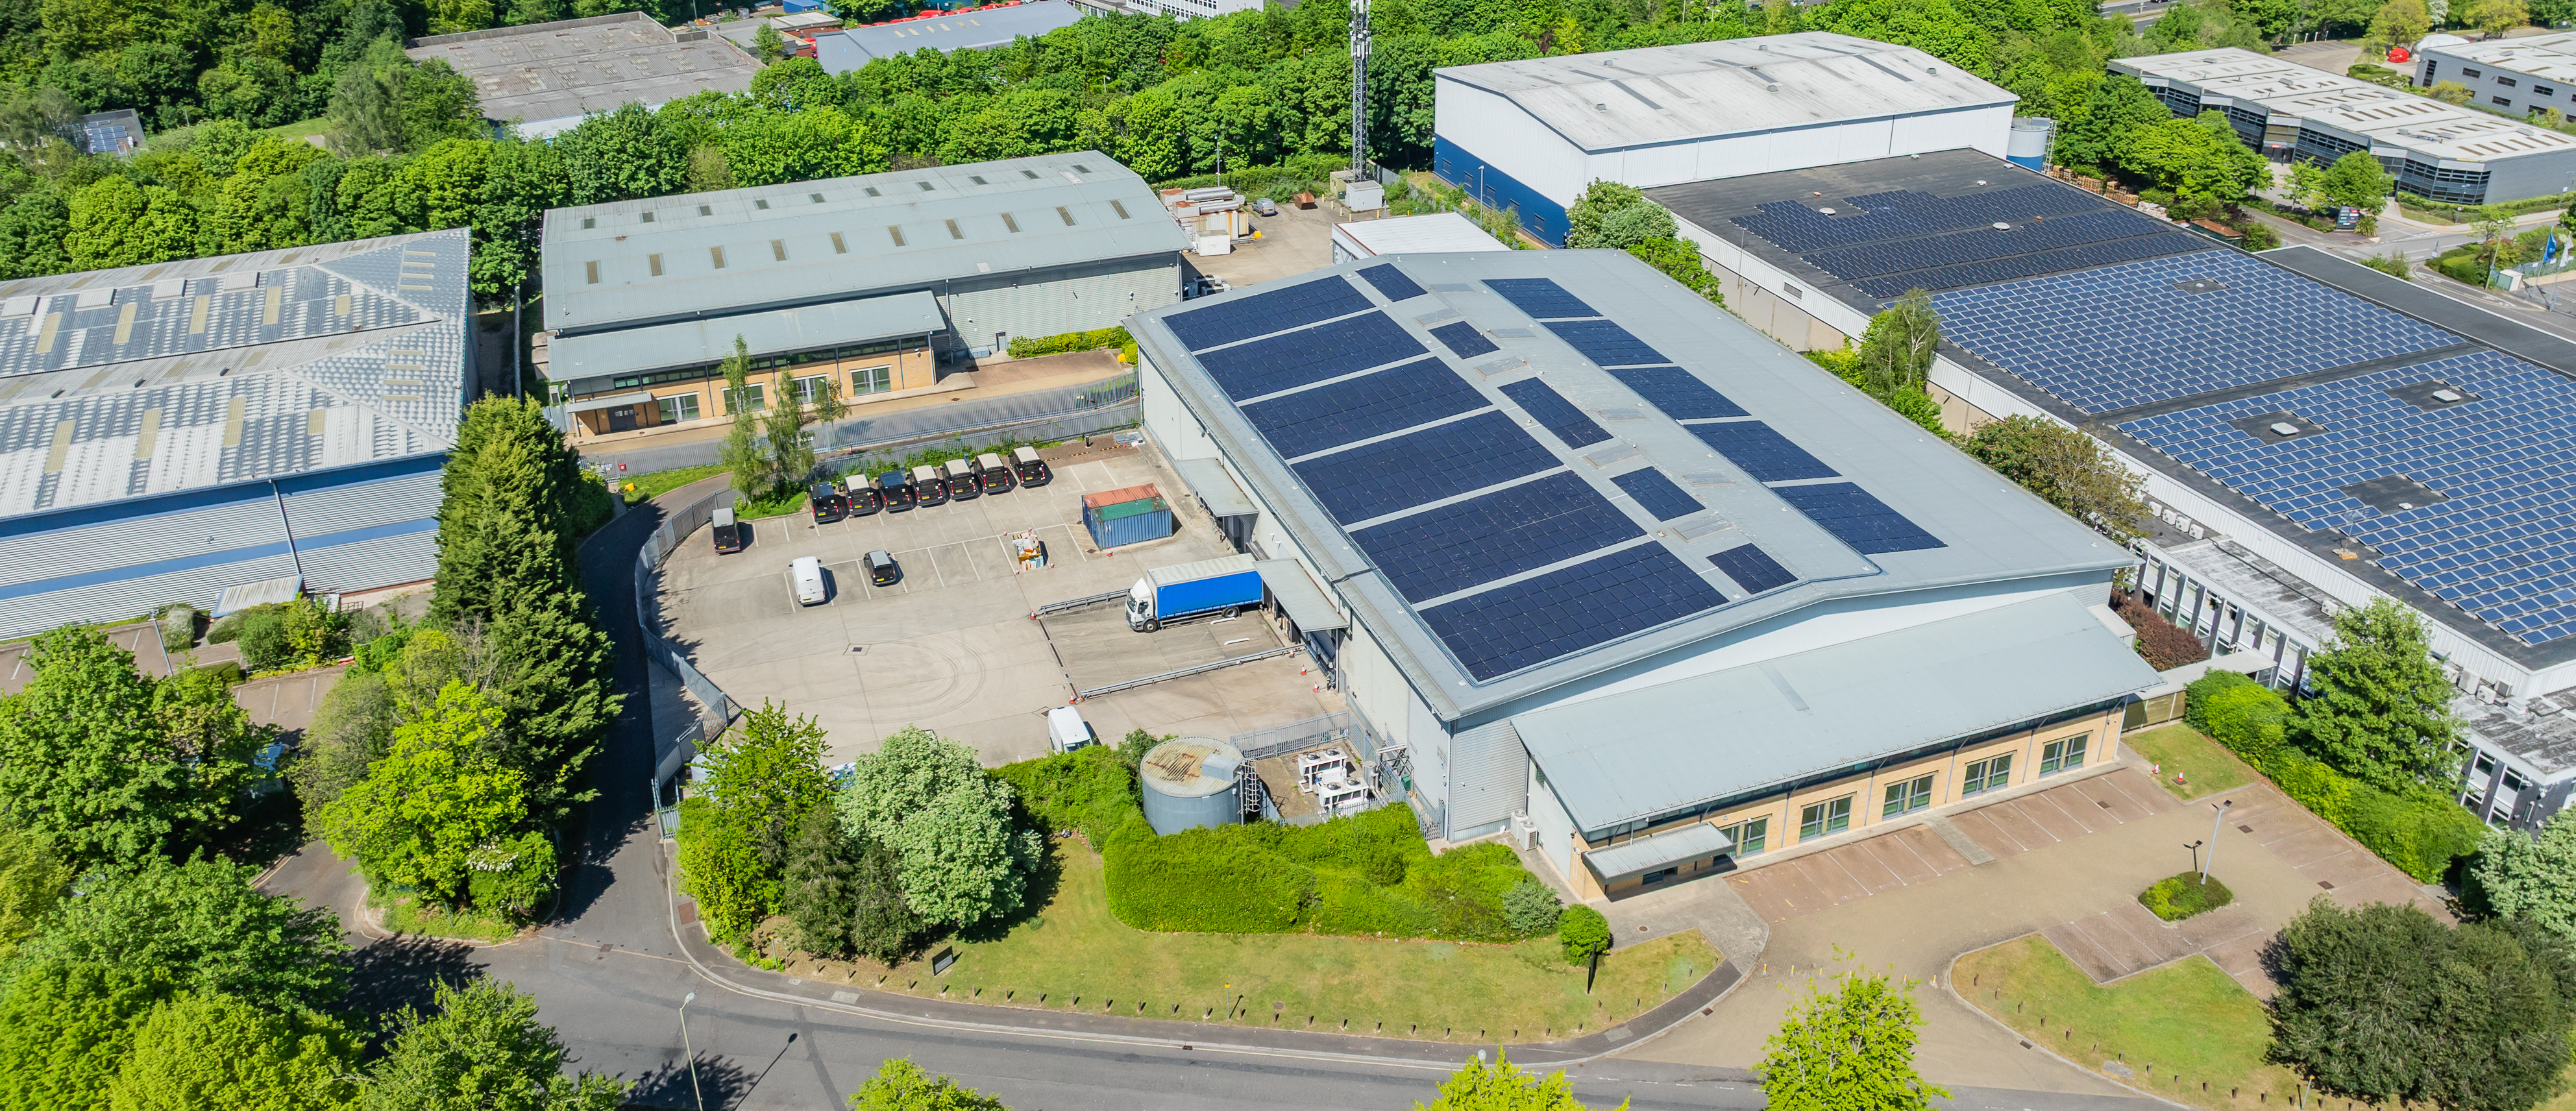
This lease is well timed because it follows on from a similar 15 year lease extension with the neighbouring property occupied by BB&R that we completed in the previous year meaning that both industrial units now are secured to institutional grade tenants for 15 year terms at significantly increased rents. At Unit 1, we extended the lease from 2027 to 2042 whilst increasing the rent from £320,000 per annum to £440,000 per annum (+37.5%). We agreed a total incentive package equivalent to 12 months rent free taken as part capital contribution and part rent free. The capital contribution has been invested in an extensive solar roof installation as well as a 6,000 litre hydrotreated vegetable oil (HVO) tank which is used by the tenant to power their fleet of delivery vehicles. This is a compelling case study demonstrating how we work with tenants to enhance the value of property assets and improve the sustainability credentials of our property holdings.
Overall, the rent across this estate has increased from £520,850 per annum at purchase in 2018 to £800,000 per annum (+54%) through our active asset management of realising two rent reviews uplifts in 2020 and 2022 and more recently two lease renewals.
This single-let logistics property was acquired in 2016. At purchase the property was let to Amazon on a 10 year lease expiring in May 2026 at a rent of £577,500 per annum. Five years later at the first rent review the rent increased to £632,206 per annum.
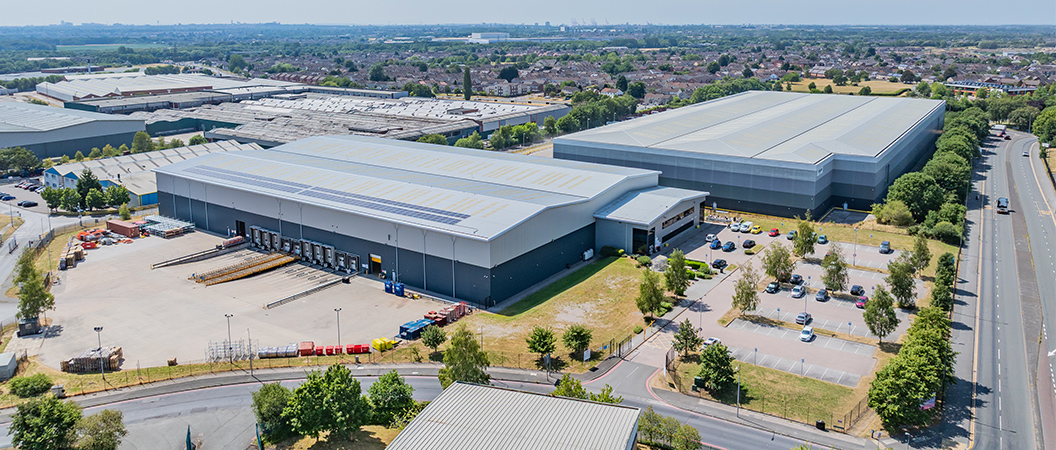
Since 2022 Amazon has sub-let the property to J Carter Sporting Club Limited, trading as Castore (sports clothing brand). In the knowledge that Amazon had no intention of reoccupying the property we approached the sub-tenant to test their appetite for a lease directly with the landlord. Terms were agreed in 2025 to surrender Amazon’s lease and simultaneously enter into a new 15 year lease directly with Castore. In early 2026 we completed the lease surrender and new lease with Castore at a rent of £835,000 per annum / £7.56 per sq ft, showing a 32% increase.
The future rent will be reviewed every fifth year in an upward only pattern to the higher of open market rent, or CPI capped at 4% per annum compound and collared at 2% per annum compound. This provides our investors with a valuable income stream secured to a good quality tenant with guaranteed future rental growth. Since purchase the rent at this asset has increased by 45% and we have experienced no void.
This multi-let industrial estate, comprising 8 units arranged in two terraces, was acquired in December 2021. The property fronts Bath Road (A4) and benefits from very good prominence as well as proximity to the city centre. Since the purchase four years ago each of the 8 units at the estate have experienced asset management interventions spanning four lease extensions, three rent reviews and a new letting. The overall rent at the estate has increased by 66% since purchase.
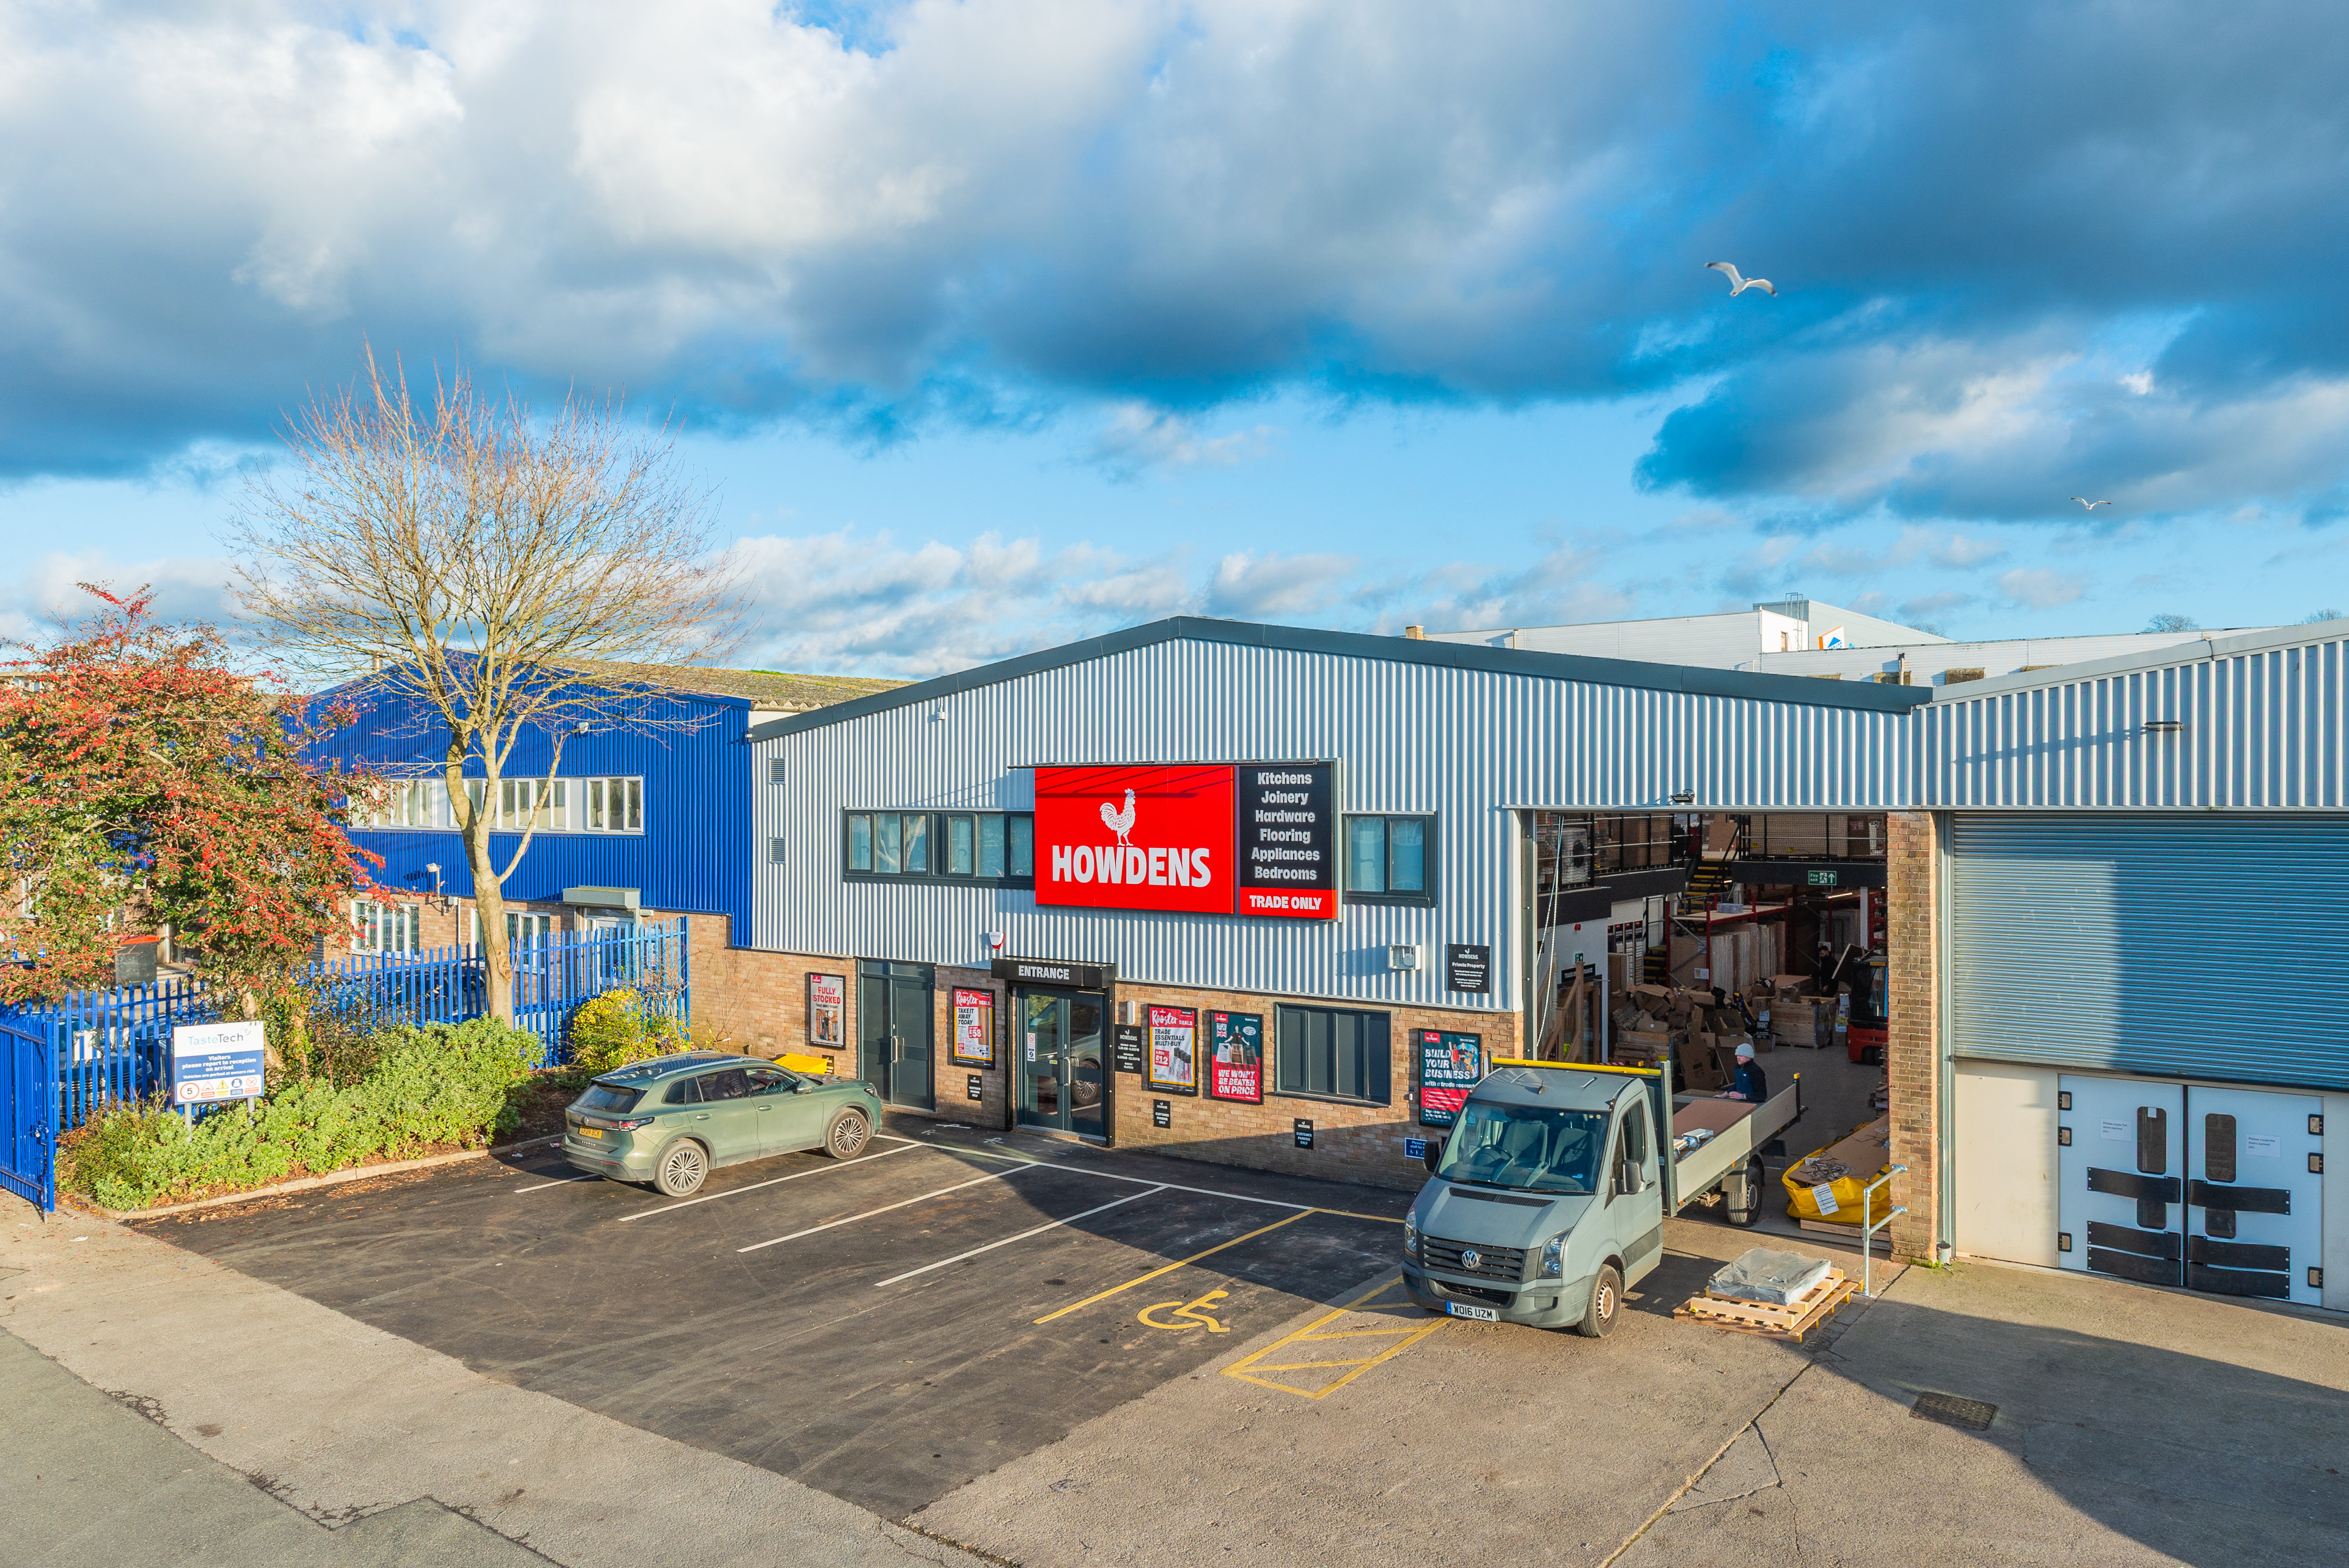
The most recent initiative involved the refurbishment and reletting of Unit 7 on the estate. The previous tenant vacated in June 2025 at expiry of their lease and we mobilised to execute a refurbishment to enable us to capture the best possible rent. The refurbishment works captured ESG interventions such as replacing the roof to improve the insulation, putting solar panels on the roof and replacing the gas with electric power. The result of these works improved the EPC rating from a D to an A. The works were executed on time and budget completing in early October. During the refurbishment period we agreed terms for a new lease with Howdens Joinery, a FTSE 100 company, at a rent of £100,000 per annum (£13.53 per sq ft) for a new 15 year lease. The lease to Howdens duly completed in October upon practical completion of the refurbishment works. This concluded a swift and accretive asset management initiative which has increased the rent by 80% compared to the rent paid by the previous occupier. Strong tenant demand is evident from our asset management experience at this estate and we think prospects remain good for future rental growth due to the prime location and limited competition within such proximity to the city centre.
The property is a Victorian warehouse converted to an office building occupying a corner position in Shoreditch on the junction of Cowper Street and Tabernacle Street. The property is a one minute walk to Old Street Roundabout.
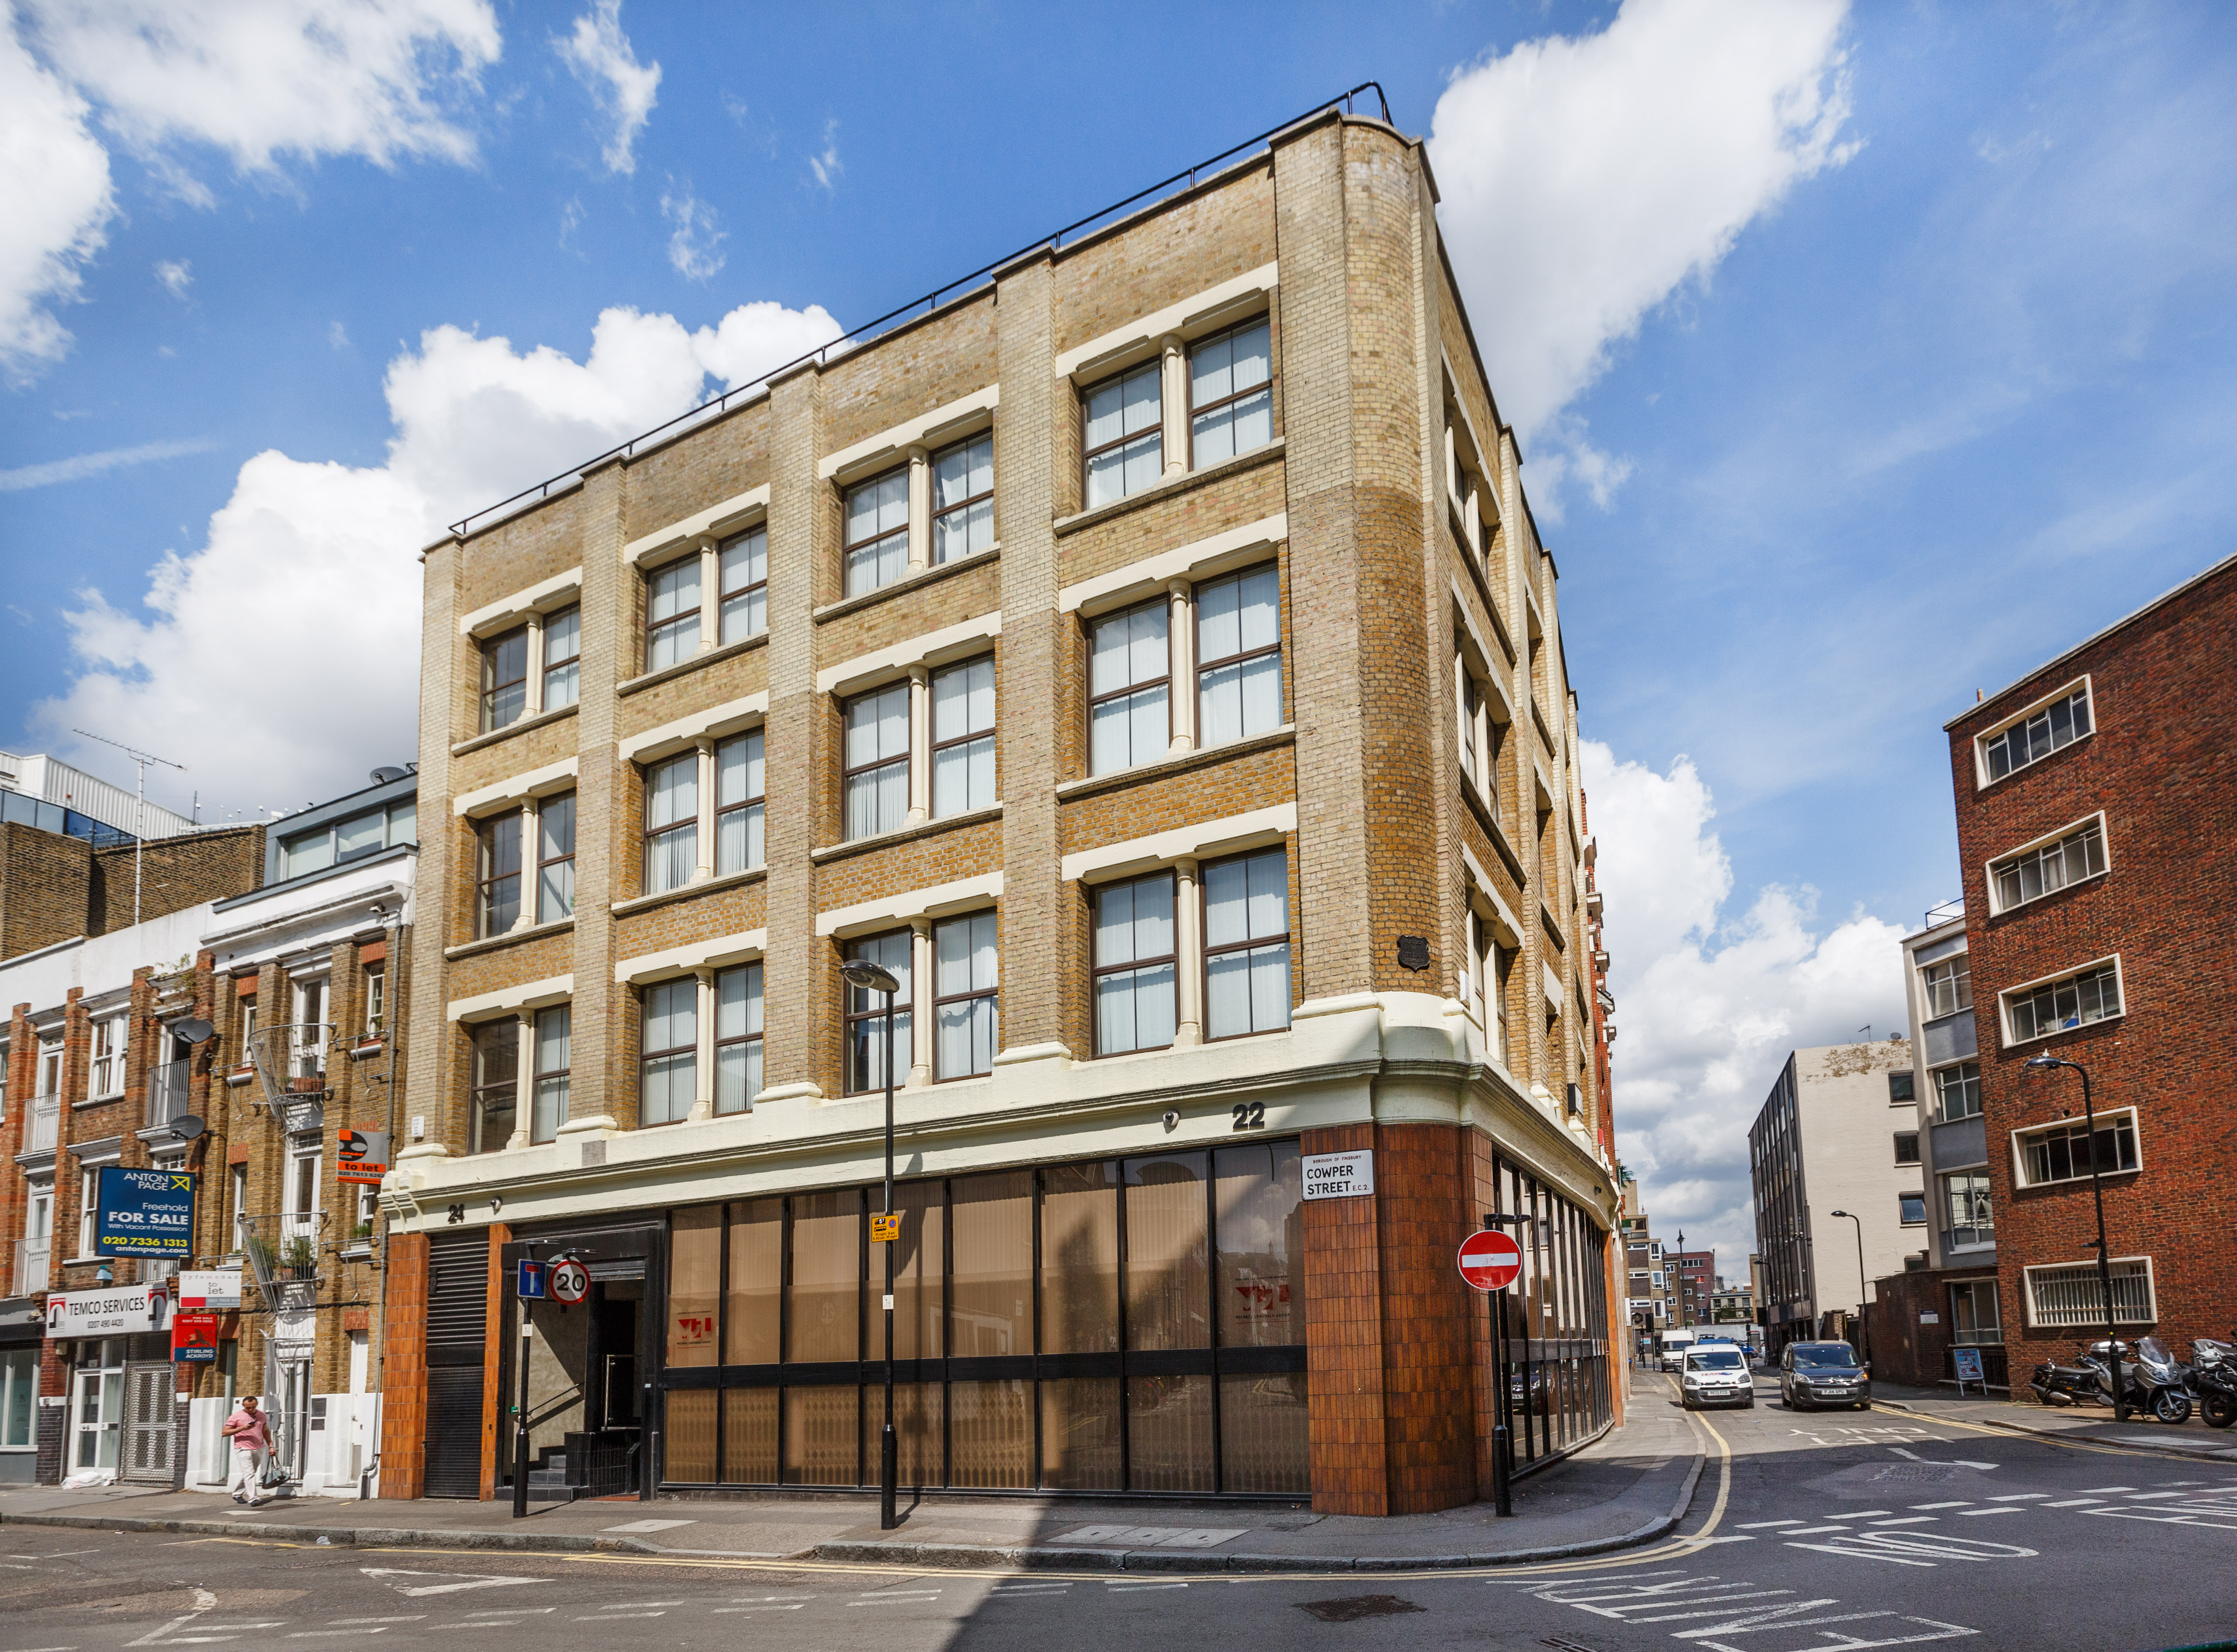
CPF acquired the property in May 2014 for £4.375 million reflecting a net initial yield of 5.50%. It was acquired as a sale and leaseback transaction, subject to a new 10 year lease with a mutual break option at year five, effective in May 2019. The rent at purchase was £255,000 per annum equating to £33 per sq ft and the lease was contracted outside of the 1954 Act.
In 2018 we served notice to break the lease to secure a higher rent from the incumbent tenant in line with the prevailing market rent (rents had increased significantly in the Shoreditch location), or we would refurbish and re-let the property. Shortly after serving the break notice, we swiftly negotiated a new five year lease with the existing tenant, again outside the 1954 Act, to commence from the break date in May 2019 at an increased rent of £425,810 pa / £55 per sq ft with three months’ rent free. This showed a 67% increase in the rent.
Having executed that asset management initiative, in the following year (2020) we received an unsolicited approach for the freehold interest. We entertained this, but opened up the opportunity to three other potential buyers including the adjoining owner and an investor with a known requirement for this type of asset who had recently been underbidder on a similar property in close proximity. We sold the property within three days of agreeing terms at a price of £9.0 million which reflected a net initial yield of 4.4% and a capital value of £1,162 per sq ft.
The investment more than doubled in value during our hold and we executed the asset management objective of increasing the rent by almost 70% without spending any capex or incurring any void and the sale was executed during the height of Covid just before Christmas 2020.
The investment delivered an IRR of 15.5% per annum.
The property stands on the west side of Chancery Lane and comprises offices arranged over lower-ground, ground and four upper floors, with two self-contained shops fronting Chancery Lane.
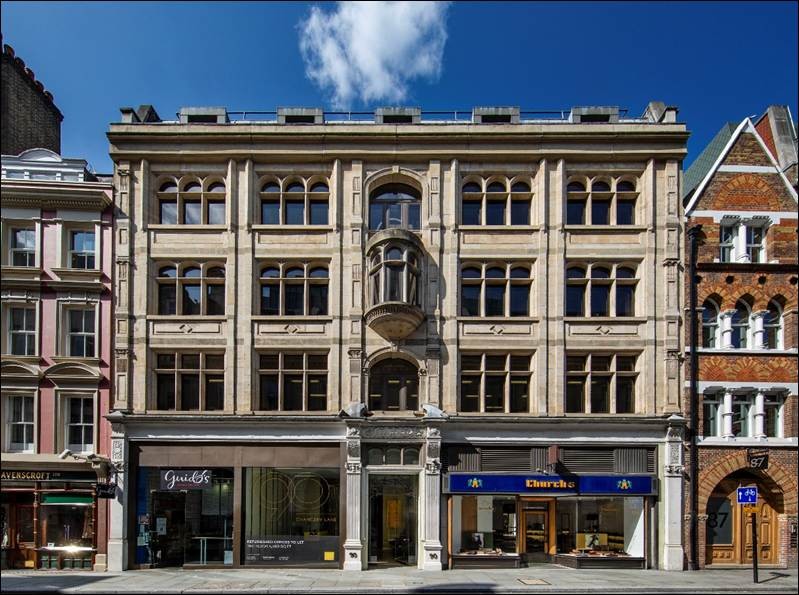
Purchased in 2004, it was previously let in its entirety to BNP Paribas. As their lease expiry in 2013 came into view the asset plan was to surrender the lease as the tenant wanted to relocate to a larger office building. 18 months before BNP’s lease expiry date we secured a cash premium to surrender their lease and we mobilised to refurbish the property achieving BREEAM Very Good rating. Bike racks and showers were added to encourage sustainable travel, and the building is DDA-compliant with full accessibility and a remodelled reception.
Having executed the refurbishment we then completed 12 lettings to eight tenants, achieving a high of £52 per sq ft – 30% above target. We continued to hold the asset as capital market conditions improved after the Euro debt crisis and rents continued to rise. This was vindicated by securing rental growth at the first cycle of rent reviews five years later in 2018 following the leasing campaign in 2013 after the refurbishment. In 2019 we felt that the rents were optimised and with favourable market conditions (Bank of England base rate was 0.75%) we marketed the freehold interest.
We experienced competitive interest from the market and sold the property at the end of 2019 to a private overseas investor for £34 million which reflected a yield of 3.7%. This turned out to be fortunate timing given that the UK entered lockdown less than three months later and the outlook for offices changed overnight.
CPF acquired the property in 2004 at a price of £17.1 million; the refurbishment cost £4.25 million; and we exited at £34 million. The asset delivered an IRR of 9.5% per annum.
The property is a retail warehouse occupying a 0.7 acre freehold site with frontage to the Old Kent Road in the Southwark, London.
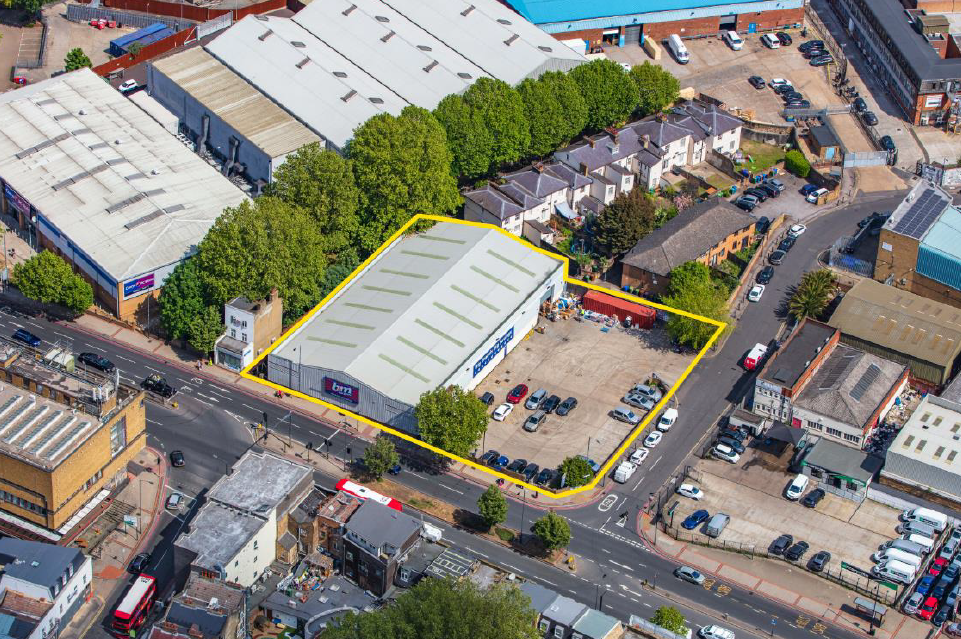
CPF acquired the freehold interest in 2001 at a price of £2.35 million. At purchase, the property was let to Magnet until 2011 at a rent of £150,000 per annum. Shortly after acquisition the 2001 rent review was settled resulting in an uplift to £257,800 per annum and the rent increased further to £305,000 per annum from 2006. Magnet vacated upon expiry of their lease in 2011 and the property was subsequently occupied by B&M on a lease expiring in 2025. The physical retail market was experiencing headwinds from online retail and rents were declining. This property was not immune from that given that the rent actually reduced to £263,250 per annum in order to secure a new occupier. However, the attraction of this asset was the large site, good frontage, London location and alternative use potential to a higher value use. Given the potential to redevelop the site we engaged planning advice to explore options and viability for a higher value use compared to retail. We commissioned a feasibility study which proposed a residential scheme extending to 17 storeys fronting the Old Kent Road with 138 apartments.
In 2019 we received an approach from a self-storage business to buy the site for £9.5 million. This was significantly above the independent valuation at the time, but we felt a better price could be extracted. Following a marketing campaign we agreed terms to sell the site to the London Borough of Southwark at £10.7 million.
The asset delivered £4.3 million in income during the ownership and a significant profit capturing an IRR of 15.6% per annum over the 18 year hold period.
These two industrial units, totalling 220,000 sq ft, were acquired in April 2014 for £11.4 million reflecting a yield of 8.4%. One unit was let to Croda plc, a FTSE 250 chemicals company, and the other was vacant; the vendor provided a 24-month rental guarantee.
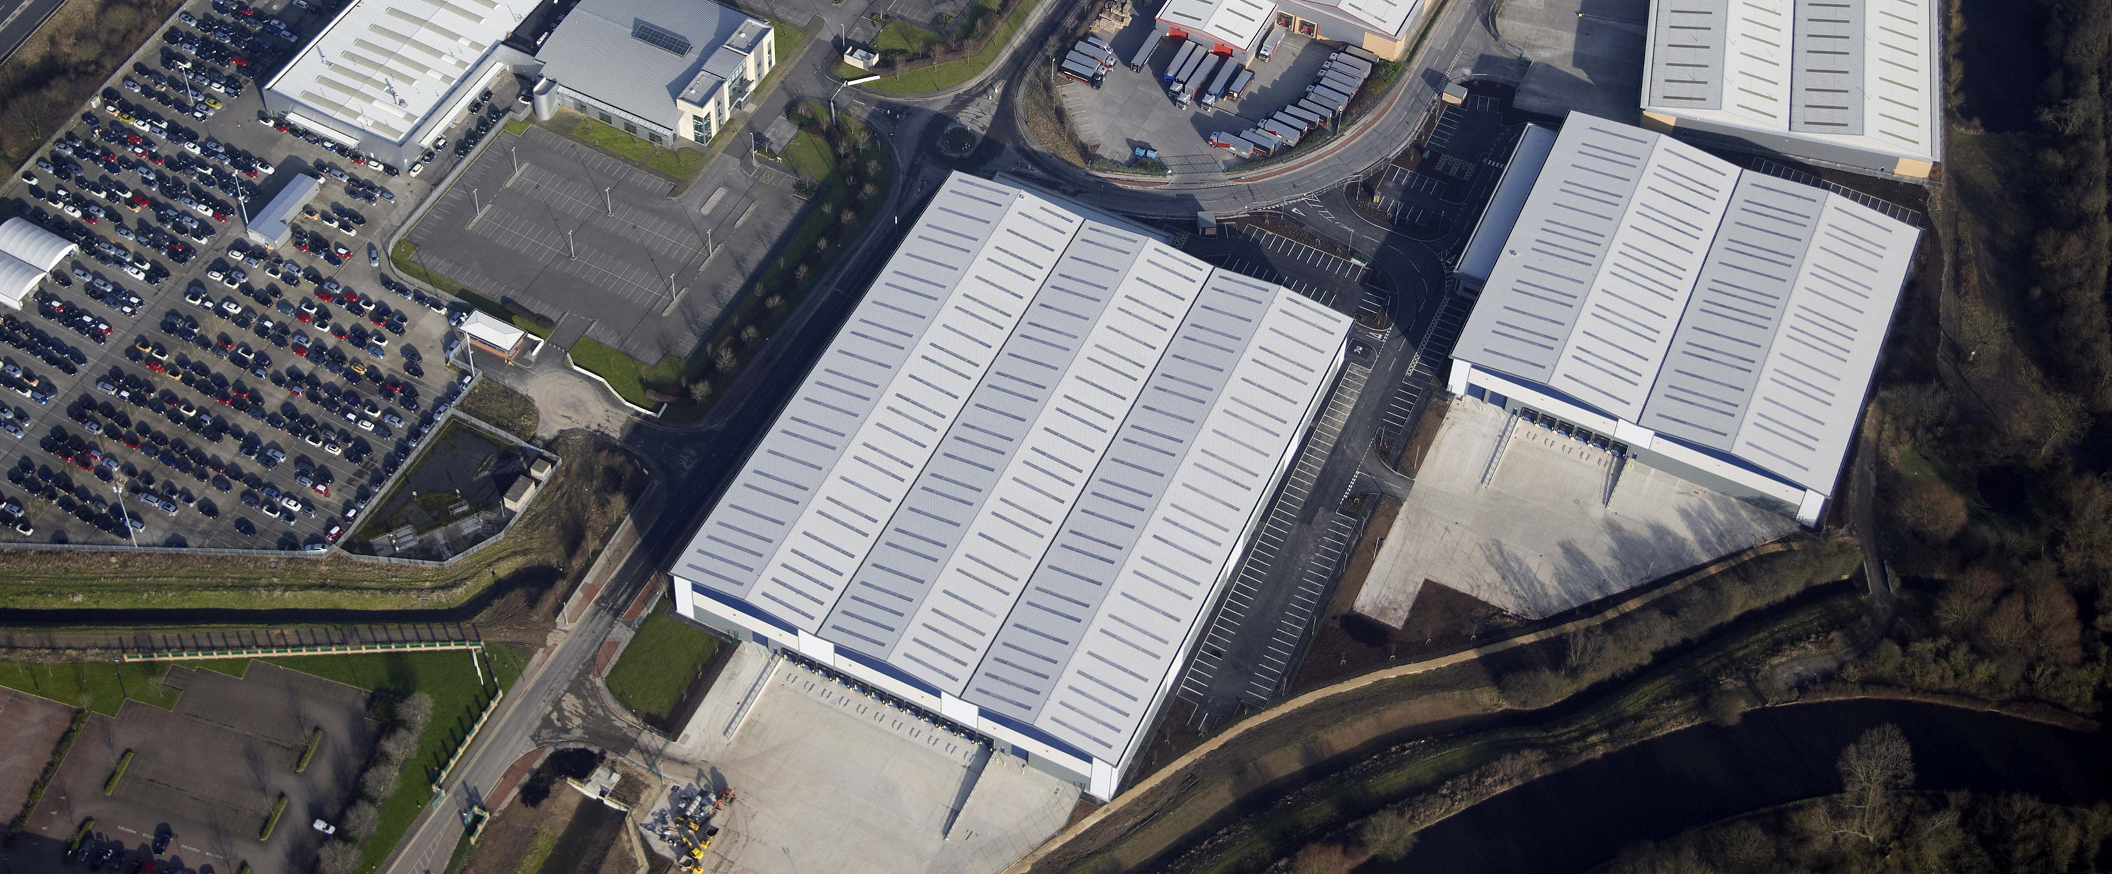
Fifteen months later, we successfully let the empty unit to Howdens Joinery on a new five-year lease at a rent of £618,650 per annum (£4.50 per sq ft), 6% above the rental guarantee. We were also able to distribute the remaining rental guarantee as a dividend.
Since purchase, we received £1.215 million from the rental guarantee and a further £650,000 in rent, as well as a £2.48 million capital profit after costs. Combined, this asset produced £4.35 million above its purchase price over the short 20-month hold period, generating an IRR of 20% per annum.
Although we generally invest for the long term, we also act opportunistically where we identify mispricing and can bring our asset management skills to good effect. After letting the empty unit, we reviewed the business plan and concluded that the new-build supply had increased significantly, meaning that the asset was no longer a suitable long-term hold. After a full marketing campaign, we sold the asset in November 2015 for £14 million, reflecting a yield of 6.9%.
This property was purchased in June 2002 for £3.7 million, reflecting a net initial yield of 7.5%. It comprises a small supermarket located on Eastwood Road, just off the High Street in Rayleigh, Essex, and was let to Somerfield on a 35-year lease from 1979, expiring in May 2014 at a rent of £294,000 per annum.
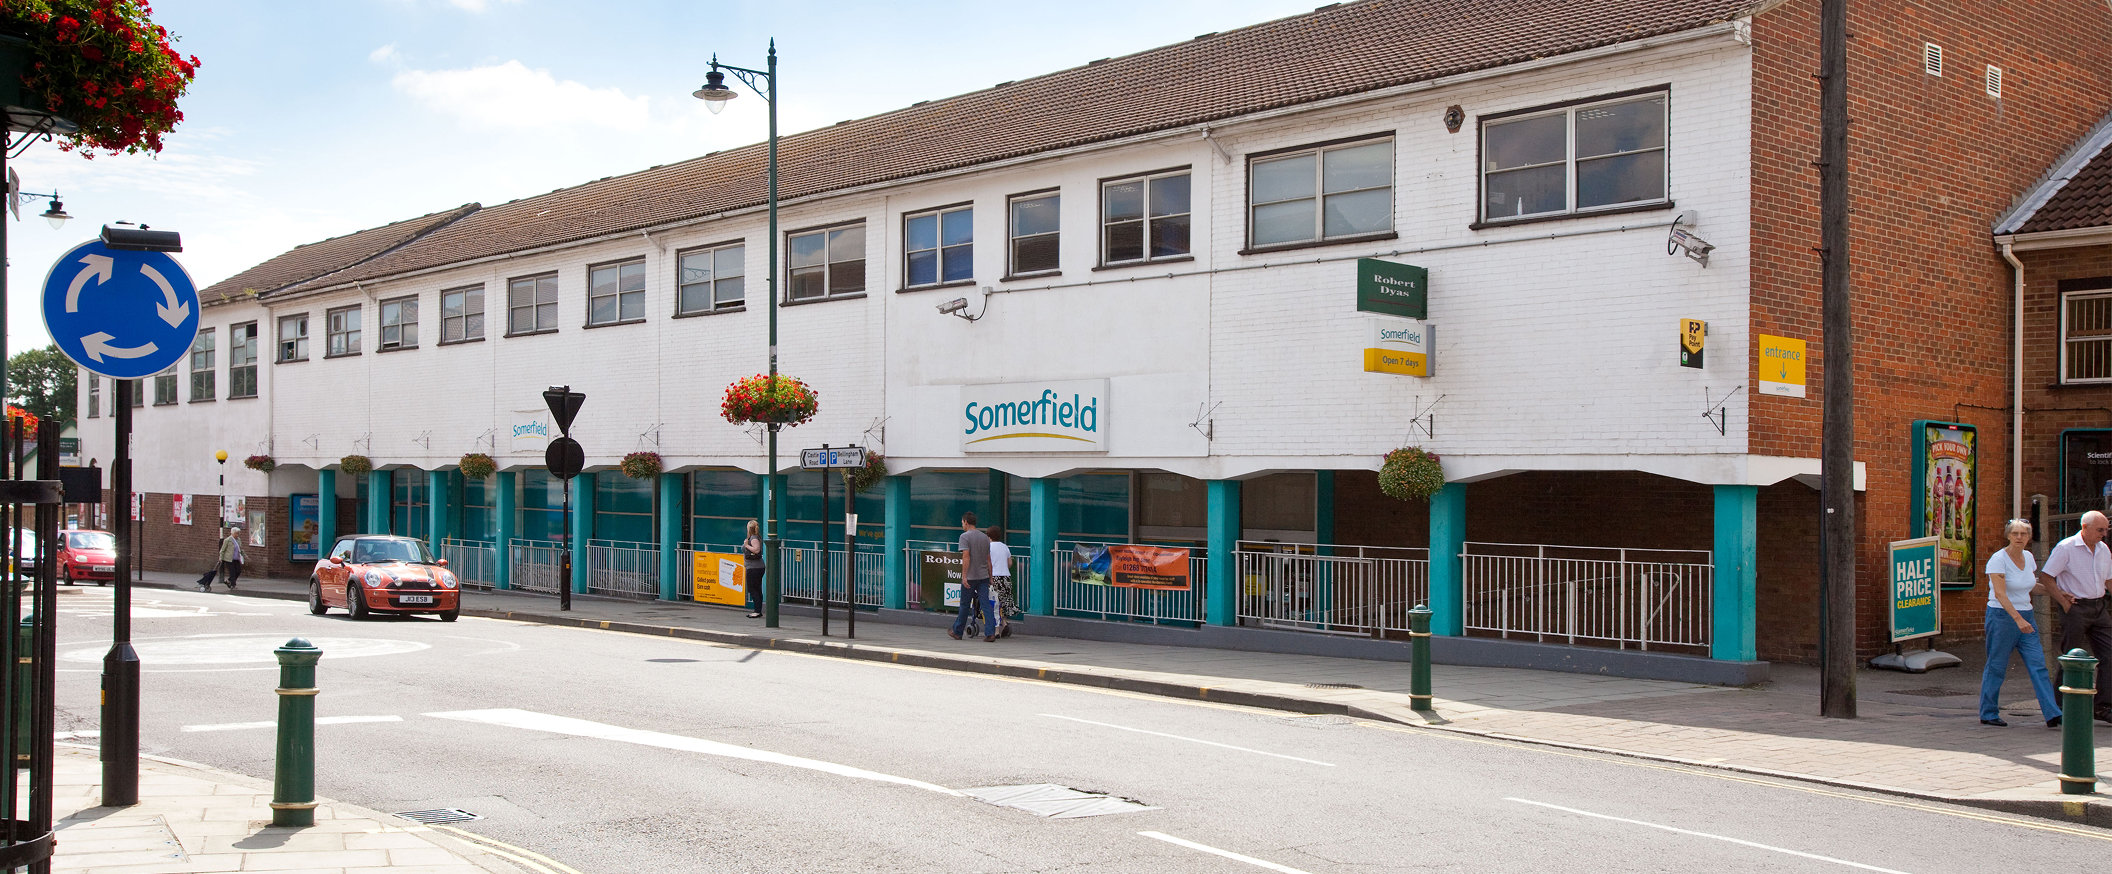
In 2010 (with only four years remaining) we commenced lease negotiations with Co-op, which subsequently signed a new 15-year lease (with a break option after 10 years) at an increased rent of £417,500 per annum – a 25.8% increase. No incentive was paid.
During its time with the Fund, the property has had three tenants, two asset management initiatives, two successful rent reviews and, finally, a sale. If we had held the asset passively, the original lease would have expired last summer; instead, it now benefits from a new 20-year term to an improved covenant.
In January 2025 the property was valued at £6.5 million, reflecting a yield of 6.1%, with five years remaining until the break option. We have since agreed to surrender the existing lease and re-let to M&S on a new 20-year term at an enhanced rent of £475,000 per annum (a 13.8% increase). M&S also agreed to five-yearly reviews to RPI, capped at 4% per annum and collared at 1% per annum. M&S was paid a premium to take this lease.
The Fund has benefited from capital growth of £5 million (after deducting the premium paid to M&S) and income of £4.74 million since purchase. This illustrates why commercial property can be such an important component of a portfolio – a strong income stream combined with capital growth enhanced through active management. The IRR over the hold period is 14% per annum.
The new lease completed in July 2015, and have now sold the asset to ICL Pension Trust for £10 million, reflecting a yield of 4.49%.
In 2016 we completed the development of a mixed-use hotel and retail scheme in Poole town centre. The property is anchored by Travelodge who pre-let the hotel on a 35 year lease with no breaks and uncapped RPI rent reviews realised every fifth year. The other principal tenant is a NHS doctors surgery with the remaining income from Costa Coffee, Trek Bicycles and a gym.
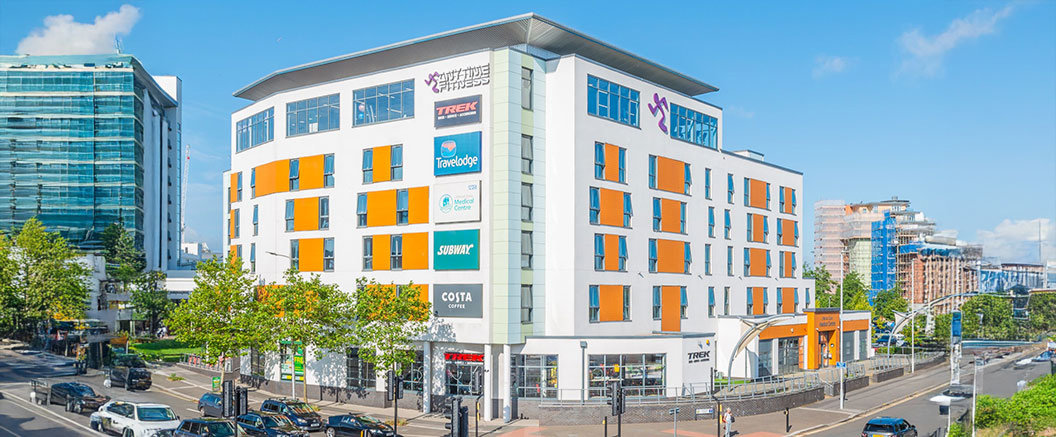
The property occupies a prominent site overlooking Poole Harbour, opposite the train station and next to a large supermarket and residential development that help drive footfall.
This follows our successful funding of the Travelodge in Cambridge, which has seen a near-50% increase in capital value against the book cost. Rental growth prospects at Poole are strong, particularly for the Travelodge income, which is let off a low rental base and represents around 60% of total income. As with Cambridge, our involvement from the outset of construction has ensured excellent energy-efficiency and sustainability credentials and once again improved the built environment.
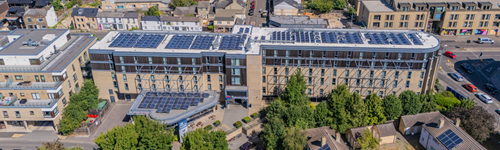
One of the Fund’s most successful projects was the forward funding of a new hotel in Cambridge. The Fund acquired the freehold site in 2011 with planning permission secured and subject to an agreement for lease, investing £16.3 million in construction, completing the landmark development on time and on budget in 2013. We received a coupon of 6% from the developer between purchasing the site and the practical completion of the development works.
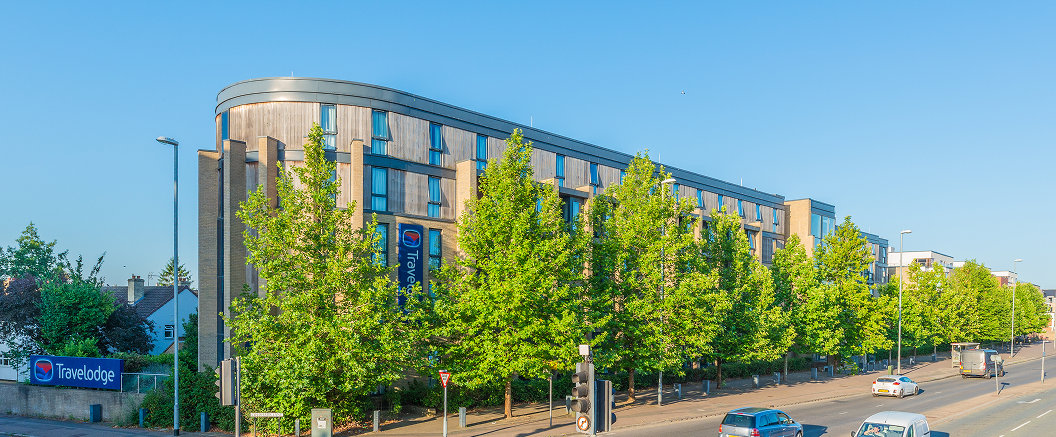
Freehold sites of this kind are scarce in Cambridge, and restrictive planning regulations make such holdings particularly valuable especially as the property value is underpinned by alternative uses. This asset has the benefit of a supply constrained location coupled with strong and diverse occupier demand. We believe the asset was undervalued at acquisition and continues to be so.
The property was pre-let on a 35-year lease to Travelodge with uncapped RPI-linked rent reviews off a low starting rent (only £5,000 per key). The developer agreed the rent with the tenant in 2008 in the depths of the global financial crisis and had two failed attempts to secure planning permission before finally securing permission in 2011. The capital invested has significantly improved the built environment in this location and further to this we insisted that the property was built to a BREEAM Very Good rating, demonstrating excellent sustainability features.
Upon practical completion of the development in 2013 the 35 year lease (no tenant breaks) commenced and as at 2023 we have been through two rent review cycles resulting in the rent increasing by approximately 50% which shows the virtue in compounding index-linked income over the long term. Importantly the rent remains affordable for the tenant and the occupier continues to invest capital refurbishing the property which is another attractive characteristic of this type of operational real estate. This property is a top ten asset by size within the portfolio and continues to be a long term hold.